Ways to Pay for Assisted Living in Texas: A Guide for Highlands Families
A practical guide for Highlands families comparing private funds, Texas Medicaid, VA pension benefits, insurance and free local guidance.
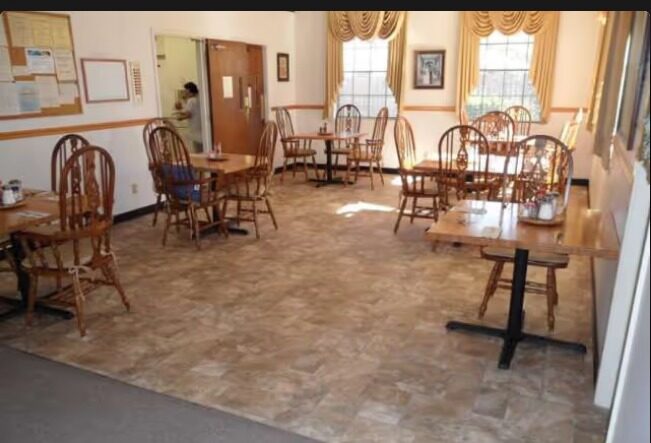
Families researching how to pay for assisted living in Texas usually need more than a monthly price. They need to know which income and benefits can be combined, what each program excludes, and how long the plan could remain workable. This guide is for adult children and spouses in Highlands, an unincorporated east Harris County community near Baytown, Crosby, Channelview and the San Jacinto River. Mountbatten House is a small nonprofit assisted living home at 213 Maple St. Public listings describe it as a Texas Type A assisted living facility; it is not a dedicated memory care community. Its current operations, services and availability should be confirmed directly.
How to Pay for Assisted Living in Texas: Begin With the Full Cost
A payment plan should separate housing and care from the other costs of daily life, then test whether the income sources can last. The CareScout Cost of Care Survey 2025 places Highlands in its Houston Area region. Its assisted living figures are medians, not quotes, and the home-care figures depend on the scheduled hours. They provide a useful baseline for Harris County families before any provider-specific fees or benefit decisions.
| Care or setting | Survey amount | Additional reference |
|---|---|---|
| Houston Area assisted living | $6,395 monthly median | $76,740 annual |
| Texas statewide assisted living | $5,666 monthly median | $67,992 annual |
| U.S. assisted living | $6,200 monthly median | $74,400 annual |
| Houston Area non-medical in-home caregiver | $29 hourly | $5,529 monthly at 44 hours/week |
| Houston Area adult day health care | $90 daily | $1,950 monthly |
The Houston Area assisted living median is $729 higher than the Texas statewide median and $195 higher than the national median. CareScout also lists non-medical in-home care at $5,529 a month for 44 hours a week. At 20 hours a week, the corresponding Houston Area estimate is $2,513 a month; around-the-clock care at 168 hours a week is $21,112. Adult day health care is listed at $1,950 monthly. These options are not interchangeable: assisted living may combine housing, meals and support, while home care leaves household costs and unpaid family coverage to consider.
Private Pay, Savings and Home Equity
Private pay is often a combination of Social Security, pensions, investment income, savings and, in some families, contributions from relatives. List dependable monthly income separately from assets that must be sold or withdrawn. Then include food or personal items not covered, transportation, insurance, taxes and an emergency reserve. Ask every provider what the quoted rate includes, how care-related charges are determined, when rates can change and which deposits or move-out terms apply. A workable budget should still make sense if one income source ends or care needs increase.
Home equity can be part of the plan, but it is not cash until it is accessed. Selling may produce net proceeds after loan payoff and transaction costs. Renting can create income along with maintenance, tax and management responsibilities. Borrowing against the home creates repayment obligations and risk. Before selling, borrowing or transferring property, discuss the consequences with a qualified Texas attorney, tax professional or financial adviser. Families considering Mountbatten House can review its rates information and care and support information, then call the home for current rates and to confirm current operations and availability.
Texas Medicaid and STAR+PLUS Assisted Living Services
Texas Medicaid’s STAR+PLUS Home and Community Based Services (HCBS) program can pay for assisted living services for members who meet nursing facility level of care. The services must be delivered in a licensed assisted living facility contracted with the member’s managed care organization, according to the Texas HHS STAR+PLUS handbook. A diagnosis alone does not establish eligibility. Families should ask about current financial and functional requirements, enrollment, assessment and provider contracting rather than assuming that moving into assisted living starts payment.
The room and board rule is especially important. Members pay room and board and any applicable copayment; STAR+PLUS should not be described as automatically covering the entire monthly bill. Interest lists or waitlists may also apply. No particular Medicaid rate or participation by Mountbatten House should be assumed. Ask the home and the managed care organization for direct confirmation, and ask who will bill for services, which charges remain with the family and what happens while an application or interest list is pending.
Texas HHS directs families to call 2-1-1 or the local Area Agency on Aging for assistance. Before relying on this program, get the name of the program, the status of any application and the next required step in writing when possible. If a community is not contracted with the member’s plan, the family may need to discuss other arrangements rather than count on reimbursement later.
VA Aid and Attendance for Eligible Veterans and Surviving Spouses
VA Aid and Attendance is an increased monthly amount added to a VA pension for eligible wartime-era Veterans or surviving spouses. Qualifying circumstances can include needing help with daily activities such as bathing, dressing or eating, being bedridden, living in a nursing home because of lost abilities, or having limited eyesight. It is not a general assisted living benefit available to every Veteran, and both pension eligibility and the applicable care criteria matter.
For rates effective December 1, 2025, the maximum annual pension rate with Aid and Attendance is $29,093 for a Veteran with no dependents and $34,488 for a Veteran with one dependent. If countable income were zero, those figures correspond to maximum monthly pensions of $2,424 and $2,874. They are ceilings for this illustration, not typical awards or guaranteed payments. VA calculates the pension by subtracting countable income from the applicable maximum rate. Certain unreimbursed medical expenses, which can include care costs, may reduce countable income when they exceed the VA threshold.
The current VA pension rate information also lists a net worth limit of $163,699 from December 1, 2025 through November 30, 2026. VA reviews certain asset transfers before a claim and can impose a penalty period, so families should not move assets simply to try to meet the limit. Surviving spouses should ask VA which rates apply to them rather than use the Veteran figures above. VA or an accredited Veterans service organization can help clarify a claim without treating the maximum rate as a promise.
Long-Term Care Insurance and Medicare Have Different Roles
Long-term care insurance may pay for assisted living, but coverage depends on the policy. Benefits commonly begin after an elimination period and when the policyholder needs help with activities of daily living or has cognitive impairment. Ask the insurer whether the specific Texas setting and license type qualify, how the elimination period is counted, what daily or monthly maximum applies, whether room and board are included, and what assessments and invoices are required. Request written confirmation. Keep paying required premiums and do not let a policy lapse while a claim or care decision is unresolved without first getting advice.
Medicare serves a different role. Medicare’s long-term care guidance says it does not cover long-term care, described there as custodial care, if that is the only care needed; most long-term care is custodial. Families should therefore not count Medicare as payment for ongoing assisted living room, board, supervision or routine help with daily activities. A separately covered health service does not turn the monthly assisted living charge into a Medicare-covered expense. Medicaid, VA pension benefits and insurance each have their own eligibility rules and should be verified independently.
Free Help for Highlands Families
Highlands families do not have to interpret every program alone. The Eldercare Locator, a service of the U.S. Administration for Community Living, connects callers with local Area Agencies on Aging at 1-800-677-1116. Because Highlands is in east Harris County and the greater Houston area, give the exact residence address and ask which agency serves it. Depending on local availability, ask about benefits counseling, caregiver support, respite information and help comparing long-term care options. These services can guide the process, but they cannot guarantee eligibility or funding.
Respite can also create time to make a careful decision. The National Institute on Aging explains that respite care gives family caregivers a short-term break and may be provided at home, through an adult day center or during a short stay in a residential setting. It is a form of care, not a standing promise to pay assisted living costs. Ask about eligibility, scheduling and charges before treating it as part of the budget, and do not assume a short stay is available at any particular home.
Match the Payment Plan to the Setting
Funding works only when the setting fits the person’s support needs. Texas HHS explains that Type A residents can evacuate without help, follow directions in an emergency and do not need routine nighttime attendance. Type B residents may need staff help to evacuate, may not follow emergency directions and may need nighttime attendance. Facilities advertising care for Alzheimer’s disease or related disorders must hold the required Alzheimer’s certification. Confirm current licensing and services directly, and discuss any change in needs before assuming the same payment arrangement will remain suitable.
The answer to how to pay for assisted living in Texas may involve several sources, but each should have a defined role. Keep a written summary of monthly income, liquid assets, quoted charges, benefit applications, remaining family responsibilities and a backup plan. Note which program covers services and which leaves room and board unpaid. Revisit the summary when health, income, caregiver availability or program rules change, so that decisions are made before a funding gap becomes an emergency.
Frequently asked questions
Does Medicare pay for assisted living in Highlands?
Medicare does not cover long-term custodial care when that is the only care needed, and most long-term care is custodial. That means families in Highlands should not budget Medicare as payment for ongoing assisted living room, board, supervision or help with daily activities. A separately covered health service does not make the assisted living monthly charge covered. Review private income, Texas Medicaid eligibility, VA benefits and any long-term care insurance instead.
Can Texas Medicaid pay the full assisted living bill?
Texas Medicaid’s STAR+PLUS Home and Community Based Services program can pay for assisted living services for members who meet nursing facility level of care, but the setting must be a licensed assisted living facility contracted with the member’s managed care organization. Members pay room and board and any applicable copayment, so it is not necessarily payment of the whole bill. Interest lists or waitlists may apply. Highlands families can call 2-1-1 or the local Area Agency on Aging.
How do Houston-area assisted living costs compare with Texas and national figures?
CareScout’s 2025 survey reports a Houston Area assisted living monthly median of $6,395, compared with $5,666 statewide in Texas and $6,200 nationally. The Houston median is therefore $729 higher than the state figure and $195 higher than the national figure. These are broad survey medians for planning, not quotes for Mountbatten House or any other residence. Ask each provider for a current written rate schedule and what it includes.
What VA Aid and Attendance figures should Highlands families know?
For Veterans with Aid and Attendance, the maximum annual pension rate is $29,093 with no dependents and $34,488 with one dependent. If countable income were zero, those annual rates correspond to maximum monthly pensions of $2,424 and $2,874; they are not automatic payments. Countable income reduces the pension. The VA net worth limit is $163,699 from December 1, 2025 through November 30, 2026. Surviving spouses should ask VA for the rate and rules that apply to them.
Where can Highlands families get free help with payment options?
Highlands families can use the Eldercare Locator at 1-800-677-1116 to find the Area Agency on Aging serving their address. Ask about benefits counseling, caregiver support, respite options and help understanding long-term care programs. For STAR+PLUS assisted living services, Texas HHS also directs families to 2-1-1 or the local Area Agency on Aging. These services can help with navigation, but they do not guarantee eligibility, funding, a contract with a particular home or immediate availability.
Talk with Mountbatten House
If you are weighing care options in Highlands, call (346) 466-0131 or plan a visit. Our team can talk through current availability, rates and next steps. Please confirm all details directly, since published figures and listings change over time.
Sources
- CareScout Cost of Care Survey 2025
- VA Aid and Attendance and Housebound benefits
- VA pension rates (current)
- Medicare: long-term care coverage
- Eldercare Locator (U.S. Administration for Community Living)
- National Institute on Aging: What is respite care?
- ACL: What is long-term care insurance
- Texas HHS: Assisted Living Facilities (ALF)
- Texas HHS STAR+PLUS Handbook 7200: Assisted Living Services
Cost figures are 2025 medians from the CareScout Cost of Care Survey and are not quotes for Mountbatten House. Program rules and benefit amounts were checked on the linked official pages in November 2026 and can change.